


09.16.2026
Experience, Relationships and Data Converge at Vontobel
09.16.2026
Vontobel’s fixed income trading desk for institutional clients covers the global fixed income universe.
The DESK connected with Jean-Michel Manry, head of fixed income trading at Vontobel‘s investments arm, for an in-depth look at the fixed income trading desk.
Vontobel manages US$142 billion globally for institutional clients. Manry’s fixed income area oversees US$32 billion.
What is the scope of the desk you lead at Vontobel for institutional clients?
The market we trade is global. This means dealing with very different instruments, currencies, jurisdictions, liquidity conditions and time zones. We have substantial activity in emerging-market bonds and less liquid securities. These segments require a particularly detailed understanding of market structure, local participants, liquidity providers, and the behavior of individual instruments.
A bond may appear liquid under normal conditions but become very difficult to trade when volatility increases. Conversely, an apparently illiquid bond may be executable if the trader identifies the right liquidity pocket, counterparty, protocol and timing.
This is where experience, market relationships and data must work together.
How do you define the role of a fixed income trading desk?
The core responsibility of the desk remains to implement portfolio managers’ investment decisions as efficiently as possible.
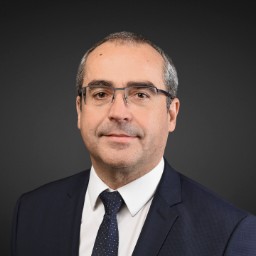
Jean-Michel Manry, Vontobel
Our first responsibility is best execution. However, best execution cannot be reduced to achieving the best visible price at a particular moment. Particularly in fixed income, it also involves understanding liquidity, market impact, information leakage, execution probability and opportunity cost.
The portfolio manager determines the investment strategy and decides which positions should be held in the portfolio. Once that decision has been made, our role is to determine how the order should be executed: which protocol to use, which counterparties to approach, how much information to disclose and how to manage the transaction over time.
Our objective is to translate the portfolio manager’s investment decision into an executed position while minimizing implementation costs and preserving investment alpha.
What makes emerging market and illiquid bond trading demanding?
The first challenge is that liquidity is highly fragmented and can change very quickly. There is rarely a single, continuously observable source of truth.
In emerging markets, two bonds with apparently similar characteristics may behave very differently because of their investor base, currency, jurisdiction, documentation or local market dynamics. The quality of execution depends on understanding not only the bond, but also who is likely to hold it, who may be willing to make a price, and how much information should be revealed to the market.
For illiquid securities, execution is not simply a question of price. You must balance price, size, urgency, information leakage and the probability of completing the transaction. Sometimes the best decision is to execute immediately. Sometimes it is to work the order patiently, change the protocol or wait for a more favorable liquidity event.
The role of the trader is to assess all these dimensions and determine which execution strategy best serves the portfolio.
You refer to preserving alpha. What does that mean from a trader’s perspective?
A strong investment idea can lose value during implementation. This may be caused by timing, market impact, information leakage, an incomplete understanding of liquidity or the selection of an inappropriate execution protocol. Preserving alpha therefore means limiting the implementation shortfall between the portfolio manager’s decision and the final execution outcome.
Price is naturally important, but it is only one part of the equation. We must also consider size, urgency, execution probability, and opportunity cost. Achieving an attractive price on a small portion of an order is not necessarily a good outcome if the remainder stays unexecuted and the market subsequently moves against the portfolio.
There is no execution method that is optimal in every situation. Our responsibility is to balance these competing objectives and adapt the execution strategy to the specific characteristics of each order.
How closely does the trading desk work with portfolio managers?
The relationship needs to be close, particularly in less liquid markets, because the trader needs to understand the context and constraints of the order.
This proximity is also physical. Our trading desk is located on the same floor, right in the middle of the portfolio management teams. This makes communication immediate and natural. A portfolio manager can speak directly with a trader as market conditions change without relying solely on systems or formal communication channels.
The portfolio manager defines the investment decision, the desired exposure, and the level of urgency. The trader then assesses the available liquidity, potential market impact and practical execution options.
This allows us to determine whether the order should be executed immediately or worked overtime, which counterparties should be approached, and which execution protocol is most appropriate.
The distinction in responsibilities remains clear. Portfolio managers make investment decisions; traders make execution decisions. Our physical proximity supports fast, continuous communication and ensures that the execution strategy remains aligned with the portfolio manager’s objectives and constraints.
Vontobel has built an internal execution database. What is its purpose?
Fixed income desks generate a considerable amount of information every day, but that information is often fragmented across trading platforms, internal systems and individual experience.
We wanted to bring these different sources together within a structured proprietary database. We capture not only completed transactions, but also the context surrounding them: RFQs, dealer responses, requested and traded volumes, execution protocols, liquidity conditions, and soon, transaction cost analysis.
This gives us a much richer view of our execution activity. We can monitor counterparty performance, response and hit rates, liquidity patterns, trading volumes, and execution outcomes across different instruments and market conditions.
Over time, the database becomes a form of institutional memory. It allows us to preserve the knowledge generated through the desk’s daily interactions with the market, test our assumptions, and make that collective experience available for subsequent execution decisions.
Market knowledge has traditionally resided primarily in the trader’s memory. Data allows us to preserve that knowledge, test it and make it scalable.
This does not mean that data replaces the trader’s experience; on the contrary, it allows us to use that experience more consistently and systematically across the desk.
How can analytics support trading?
We have developed proprietary analytics tools through a series of R Shiny applications. They are designed around the desk’s workflow and the questions traders need to answer in real time.
The applications allow us to monitor counterparty behaviour, liquidity, transaction cost analysis, RFQ activity, requested and traded volumes, hit rates, and response rates.
Because the tools draw on our structured data, we can move quickly from a high-level view of activity to a detailed analysis of a particular bond, counterparty or execution.
One especially valuable capability is the speed with which we can identify and analyse comparable bonds. Within a very short time, the trader can examine securities with similar characteristics and assess where a bond appears rich or cheap relative to the relevant curve.
This does not generate an investment recommendation or replace the portfolio manager’s analysis, but it gives the trader an informed reference range for the execution, particularly where the bond itself has limited observable trading activity.
In emerging markets and illiquid segments, we can combine comparable-bond analysis, curve positioning, historical RFQs, previous executions and current dealer indications to assess where a transaction may realistically be executed.
The purpose is to give the trader a richer and more relevant information set when selecting and managing the execution strategy.
Have your proprietary analytics tools changed how traders make execution decisions?
Yes, because traders can combine current market information with evidence from our previous execution activity.
Before approaching the market, we can build a more informed view of how the security or comparable securities have traded, which counterparties have historically been relevant, and which execution protocol may be most appropriate.
The tools do not make the decision for the trader. Markets change, and historical observations must always be interpreted within the current context. However, the trader begins the execution process with a richer and more structured information set.
Data can challenge an intuition, confirm it, or reveal an execution pattern that would otherwise have remained invisible. Experience remains essential for interpreting that evidence and deciding whether a historical pattern remains relevant.
In fixed income, data does not replace market experience – it makes that experience scalable.
What is rapid comparable-bond analysis, and how is it deployed?
It strengthens our ability to assess execution conditions, particularly when a bond has limited observable liquidity.
The portfolio manager has already made the investment decision. Our comparable-bond analysis helps us estimate a realistic execution range, evaluate dealer indications, and understand whether the prices received are consistent with the relevant curve and current market conditions.
It also helps us determine how to approach the transaction. If observable liquidity is limited, we may decide to target a smaller number of relevant counterparties, manage the order more discreetly, or execute it progressively.
The value is therefore primarily in execution preparation, price assessment, and liquidity management. It does not change the division of responsibilities between the portfolio manager and the trading desk.
Transaction cost analysis (TCA) is well-established for liquid bonds. Can it work for illiquid bonds?
It can, but only if we recognize its limitations. In illiquid fixed income, there may be no perfect benchmark and no continuously observable market price. A single metric can therefore create a false sense of precision.
We prefer to examine execution through multiple lenses: the information available before the trade, comparable instruments, dealer responses, bid-offer dispersion, market developments after execution, completion rates, and opportunity cost.
Context is essential. A transaction may appear expensive relative to a theoretical benchmark, but still represent an excellent outcome given its size, urgency and liquidity risk.
Conversely, an attractive price on a relatively small completed portion of an order may not represent a good overall result if the remainder remains unexecuted.
Transaction cost analysis should therefore be used as a learning tool, not simply as a scorecard. Its purpose is to improve future execution decisions rather than encourage traders to optimize a single indicator.
How do you use data to evaluate and select counterparties?
We analyze counterparty performance across several dimensions rather than relying on a single league table.
Our proprietary tools allow us to examine hit rates and executed volumes, pricing quality, areas of liquidity, and performance under different market conditions. We can also distinguish between a counterparty that responds frequently and one that provides genuinely actionable liquidity.
This helps us direct RFQs more intelligently. Sending every enquiry to every dealer does not necessarily improve execution. It may create unnecessary information leakage without increasing the probability of finding meaningful liquidity.
The objective is to identify the counterparties that are most relevant for a specific bond, sector, region or type of transaction. Data makes this process more disciplined, while the trader’s market knowledge helps us understand what sits behind the numbers.
A dealer may have access to a particular pocket of liquidity or possess valuable local knowledge that is not immediately visible in aggregate statistics. This is why quantitative evidence and qualitative judgement must remain complementary.
How do you see the balance between electronic trading and voice execution?
I do not see them as competing models. They are different tools that should be used according to the characteristics of the transaction.
Electronic protocols have brought significant benefits to fixed income: broader access to liquidity, faster price discovery, greater efficiency, improved traceability, and much better data capture. For smaller or more standardized orders, a high degree of automation can be entirely appropriate.
However, emerging market and illiquid bonds often require more discretion. The trader may need to manage information carefully, identify a natural counterparty, negotiate structure or size, and understand a dealer’s real appetite. In these situations, human interaction remains extremely important.
The future will be hybrid. More routine activity will be automated, while traders will devote more attention to complex orders, liquidity discovery, protocol selection and execution strategy.
The question is not whether a trade should be electronic or voice; the question is which protocol will produce the best outcome for that particular order.
How far can execution be automated?
Many elements can be automated: order enrichment, classification, initial protocol selection, certain RFQs, controls, and parts of the post-trade analysis.
However, automating a process does not mean giving up control. Effective automation must operate within a clearly defined framework, with understandable parameters, risk thresholds and escalation mechanisms.
The objective is to free traders from repetitive tasks so that they can devote more time to decisions where their judgement creates the greatest value.
We should not measure the success of automation solely by the percentage of trades processed without human intervention. We should measure whether it improves consistency, reduces operational risk, and allows the desk to focus more effectively on complex liquidity.
How do you incorporate new issues into your workflow?
New issues are operationally complex because the final security does not yet exist when the investment process begins. The ISIN and complete security details may only become available relatively late in the process.
We have addressed the first part of this challenge internally by creating a temporary security. Portfolio managers can submit their orders against this provisional instrument, enabling us to capture and manage the complete lifecycle of each request, from the initial PM order through to the final internal allocation. Once the ISIN and definitive security details become available, the provisional instrument is automatically enriched with the final security data. This provides us with a structured, traceable and auditable workflow before the bond has formally been created.
The remaining challenge is the last mile: automating the placement of orders with lead managers. We currently monitor two principal platforms and are making progress in developing FIX connectivity with both. However, neither platform covers the full universe of lead managers involved in new issues.
There is some overlap between the two platforms, which can create additional complexity, and certain lead managers are still not available on either platform. Consequently, the buy side must continue to operate across a combination of platforms and manual communication channels.
The objective should be a fully connected workflow, from the portfolio manager’s initial order, through order placement and book updates, to the final allocation and creation of the security in our systems.
We have made substantial progress in automating and controlling the internal part of this lifecycle. Completing the external part will require broader dealer participation, greater interoperability between platforms, and more standardized connectivity across the new-issue ecosystem.
The industry does not simply need another new-issue platform; it needs greater interoperability across the entire new-issue ecosystem.
What role will artificial intelligence play on the fixed income desk?
Artificial intelligence has the potential to accelerate the interpretation of increasingly large and complex datasets. It may help identify patterns, classify orders, detect anomalies and improve the contextual information available to the trader.
But, its usefulness will depend on the quality of the underlying data. If the information is incomplete, inconsistent, or poorly understood, a more sophisticated model will not solve the problem. This is why building a strong and structured data foundation is so important.
Governance and explainability will also be critical. Traders need to understand why a tool is producing a recommendation, and under which circumstances that recommendation may be unreliable.
I see AI as an augmentation tool. It can help traders process more information, recognize patterns more quickly, and focus their attention more effectively. However, accountability for the execution decision must remain clear.
What qualities do you look for in the next generation of traders?
Curiosity is probably the first quality. Traders need to understand markets and instruments, but they also need to understand data, technology and the objectives of the portfolio.
They must be comfortable using quantitative tools without losing their ability to communicate, negotiate and make decisions under pressure. They must also be willing to challenge established habits. A method that worked well historically is not necessarily the best approach in a market whose structure continues to evolve.
I look for people who can combine analytical discipline, market judgement, collaboration, and a strong sense of responsibility.
The more powerful our tools become, the more important human discernment becomes.
What will distinguish leading buy-side trading desks over the next five years?
The leading desks will be those that successfully combine three elements: market expertise, structured data, and technological agility.
Technology alone will not be enough. Systems can be acquired, but it is much harder to create a culture in which traders understand data and technology and use both effectively in their daily decision-making.
The distinction between execution, analytics, and technology will continue to narrow. Routine flows will become increasingly automated, while traders will focus more on complex liquidity, counterparty strategy, protocol selection, and the supervision of execution tools.
The desk of the future will not simply execute more quickly. It will learn from every RFQ and every transaction to improve subsequent execution decisions.
Our objective is to transform every RFQ and every execution into reusable execution intelligence. That is where I believe the greatest strategic value will be created.

NEWSLETTER SIGN UP
And receive exclusive articles on securities markets

🏆 The 2026 Global Markets Choice Awards are here! 🌍 Nominations are officially OPEN for the celebration of excellence in global capital markets trading & technology. Nominate below:
https://www.jotform.com/form/260086385121150

Delaware Life Insurance Company is becoming the first insurance carrier to offer an index that contains cryptocurrency, adding the BlackRock U.S. Equity Bitcoin Balanced Risk 12% Index to its fixed index annuity (FIA) portfolio.
As the digital assets industry pushes toward
Franklin Templeton is expanding its tokenized fund suite, signaling growing institutional demand for blockchain-based fund infrastructure and regulated investment products moving onchain. Read the full article below:
$50 billion in active ETF inflows helped fuel a record year for @BlackRock 's iShares business, as investors continue to lean into active strategies.
Terry Flanagan
Managing Editor
Terry Flanagan is Managing Director at Markets Media Group, where he oversees the Markets Media, Traders Magazine, and GlobalTrading platforms....
More about this authorRelated articles
-
Platform is a one-stop shop for buy side and corporates to tap into data, analytics and trade execution.
-
"Having a focused area – a center of excellence – is a large part of our narrative."
-
Buy-side desks have seen no shortage of shocks in the first quarter.
-
Long-time buy side trader discusses his career, the evolution of the industry, and what's next.
-
Franklin Templeton's David Lewis says tech evolution forces traders to periodically reinvent themselves.