


09.21.2026
BMO ‘Last Call’ Aims to Trade Into the Close Opportunistically
09.21.2026
As volume increasingly aggregates around the closing auction on stock exchanges, BMO Capital Markets is launching an algorithm that can trade this aggregation of liquidity more opportunistically.
Eric Stockland, co-head of global electronic trading at BMO Capital Markets, described the new algo, Last Call, as being built around opportunistic non-completion as it focuses on the last 15 minutes of the trading day.
Eric Stockland, BMO
Stockland told Markets Media: “A lot of people have liquidity problems and tricky names to trade. This algo is built for folks who are not necessarily targeting the closing price, or who do not need to complete their whole ticket, but who are opportunistically looking for good liquidity at the right price.”
For example, the algo may trade 100% of the ticket or 1% of the ticket, depending on market conditions, with the emphasis on not impacting the price for the next day if the ticket is not completed.
“Some really aggressive, opportunistic trading takes place around the final seconds of the trading day, and the algo brings together these disparate tactics to make it truly dynamic and intelligent into the close,” he added.
Kathryn Zhao, head of API product at crypto exchange OKX, told Markets Media that volumes in closing auctions have continued to grow, driven in part by the rise of passive investing (index funds and ETFs), which require closing prices to minimize the tracking error.
“Institutional traders and algorithmic strategies also cluster at the close to take advantage of this deepest pool of liquidity and minimize price impact,” she said.
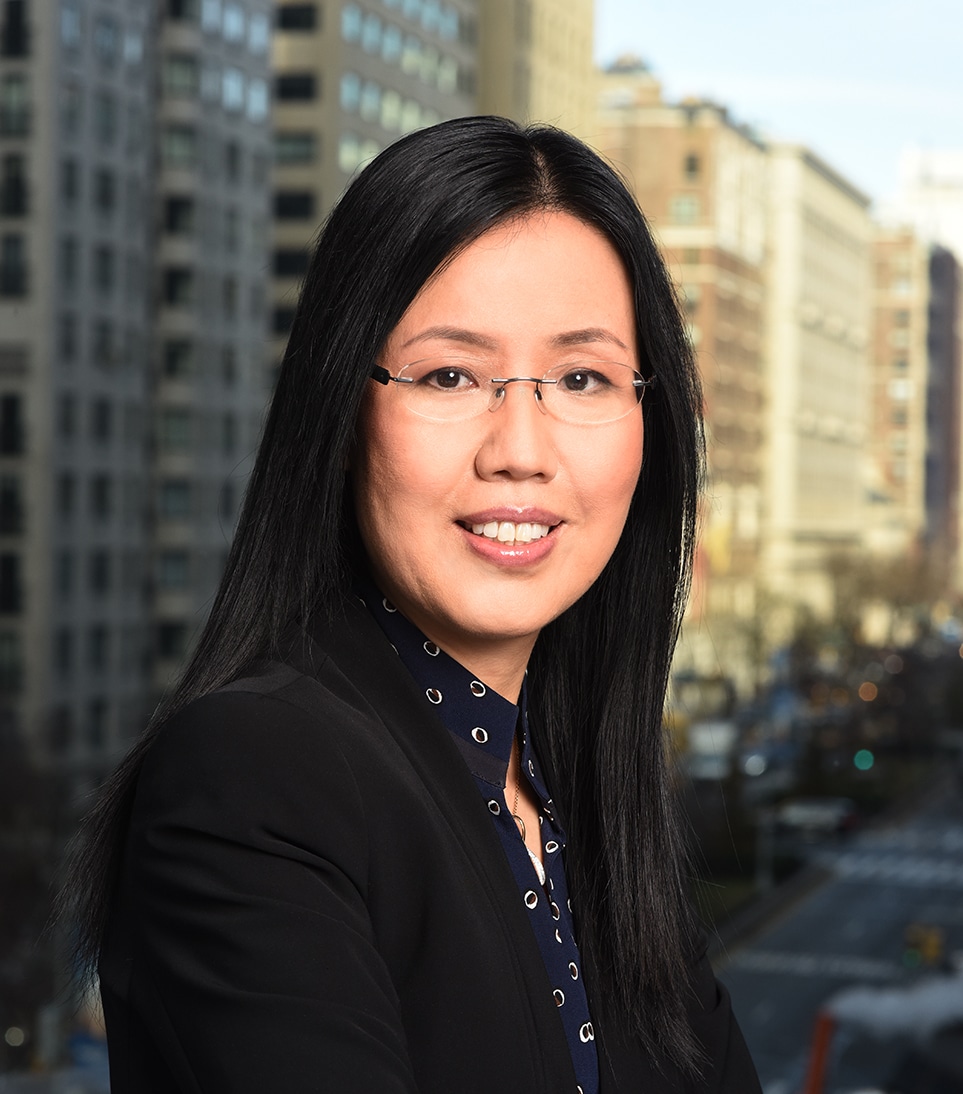
Kathryn Zhao, OKX
Zhao was previously global head of electronic trading at broker Cantor Fitzgerald, where she successfully rolled out the algorithmic trading suite including the Precision algo platform. She explained that designing algorithms for closing auctions involves many nuances, since these orders can be large or small, they can carry volume or price limits, and requirements often vary from client to client.
In addition, clients who trade in closing auctions vary in their priorities. Zhao added that some clients are highly focused on minimizing market impact, while others weigh different constraints more heavily. In addition, market microstructures also differ across venues. NYSE’s D-Orders, for instance, allow an order to be submitted as late as 3:59:50 p.m., though at a higher cost.
She said: “In my view, closing auction liquidity is unlikely to decline — it will either plateau or continue rising, potentially at a slower pace.”
Between 2020 and 2025, the share of closing auctions generally increased, in terms of value traded, according to a report from IOSCO in May this year. The securities regulator said in a report: “In certain jurisdictions (notably in Europe), the proportion of the amount executed during the end-of-day closing auction relative to total daily trading value has risen by as much as 10%.”
IOSCO’s Consultation Report on the Evolution of Market Liquidity during the Trading Day said equity market structures continue to evolve, with technological developments and trading strategies contributing to a growing concentration of trading activities at the close in many jurisdictions.
In terms of execution risk, a paper in the Journal of Financial and Quantitative Analysis in March 2026 analyzed the price impact in closing auctions. The paper, Price Impact in Closing Auctions, Opening Auctions, and Continuous Markets: A Benchmark for Cost of Trading on Anomalies, by Amit Goyal, Narasimhan Jegadeesh and Yanbin Wu found that the price impact is lower in closing auctions than in the continuous market for all stocks except Nasdaq microcaps.
“The annualized trading costs for long/short portfolios based on financial ratios such as profitability and investment range from 17 to 41 basis points (bps), said the paper. “Excluding microcaps, these costs fall to 9 – 21 bps in closing auctions.”
In contrast, researchers found that opening auctions are illiquid and have relatively large price impacts.
Last Call
Antonio Trillo, co-head of global electronic trading at BMO Capital Markets, told Markets Media there is a big distinction between the closing volume print and the volume into the last minutes of the trading day, which is a big focus for this new algo. BMO estimated that approximately 15% of the average daily volume of a stock can trade in the last 15 minutes of the day, not including the close.
“This brings a lot of coordination between how investors target the close, participate in the trade opportunistically around the close and seek liquidity in a really smart, delicate way to minimize price impact,” he added.
Trillo explained that clients are giving BMO greater discretion to take on risk in large blocks because the algo is not required to complete the order that day, allowing it to prioritize price quality.
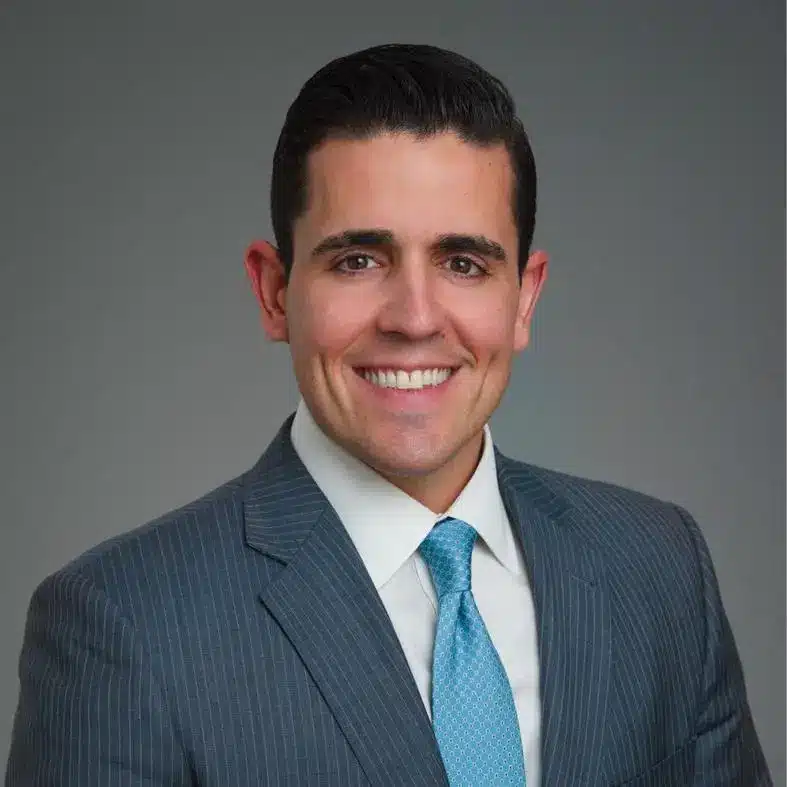
Antonio Trillo, BMO
“They do not want to see the stock break or decline massively in the last 15 minutes as traditional algorithms behave into the close,” he said. “Last Call is balancing order entry price, the closing price, and ultimately prioritizing the liquidity event itself in order to achieve an optimal risk transfer outcome for the end user.”
Stockland continued that clients are really busy and under a ton of stress at the end of each day. He added: “We are asking for them to outsource the intelligence and the settings to us based on their urgency. We take care of all the details underneath the hood.”
As closing auctions and end-of-day liquidity continue to grow in importance, market participants are increasingly seeking execution strategies that can adapt to evolving trading dynamics. BMO’s Last Call is designed to help clients access liquidity opportunistically around the close while prioritizing price quality and flexibility over completion at any cost, according to Stockland. He said: “I think we have built something really special.”

NEWSLETTER SIGN UP
And receive exclusive articles on securities markets

🏆 The 2026 Global Markets Choice Awards are here! 🌍 Nominations are officially OPEN for the celebration of excellence in global capital markets trading & technology. Nominate below:
https://www.jotform.com/form/260086385121150

Delaware Life Insurance Company is becoming the first insurance carrier to offer an index that contains cryptocurrency, adding the BlackRock U.S. Equity Bitcoin Balanced Risk 12% Index to its fixed index annuity (FIA) portfolio.
As the digital assets industry pushes toward
Franklin Templeton is expanding its tokenized fund suite, signaling growing institutional demand for blockchain-based fund infrastructure and regulated investment products moving onchain. Read the full article below:
$50 billion in active ETF inflows helped fuel a record year for @BlackRock 's iShares business, as investors continue to lean into active strategies.
Shanny Basar
Senior writer
A Senior Writer at Markets Media who became a financial journalist in 2000 after working in banking for over a decade....
More about this authorRelated articles
-
The AI-native interface for trading analytics enables institutions to optimize execution costs before trading.
-
The firm is the first FCM to provide access to Kalshi and has launched Clear Street Private Markets.
-
The firm has extended algorithmic trading beyond the U.S. and Canada for the first time.
-
Members can source block liquidity while working algorithmic strategies in the broader marketplace.
-
The integration of dbHedge into LiquidityFX augments smartTrade’s existing tools for internalising FX flow.